Flood insurance vs homeowners insurance: what Bradenton residents need to know
Homeowners insurance in Bradenton almost never covers flooding. Here's the real difference between the two policies, what each costs in 2026, and how to file a claim that actually pays.
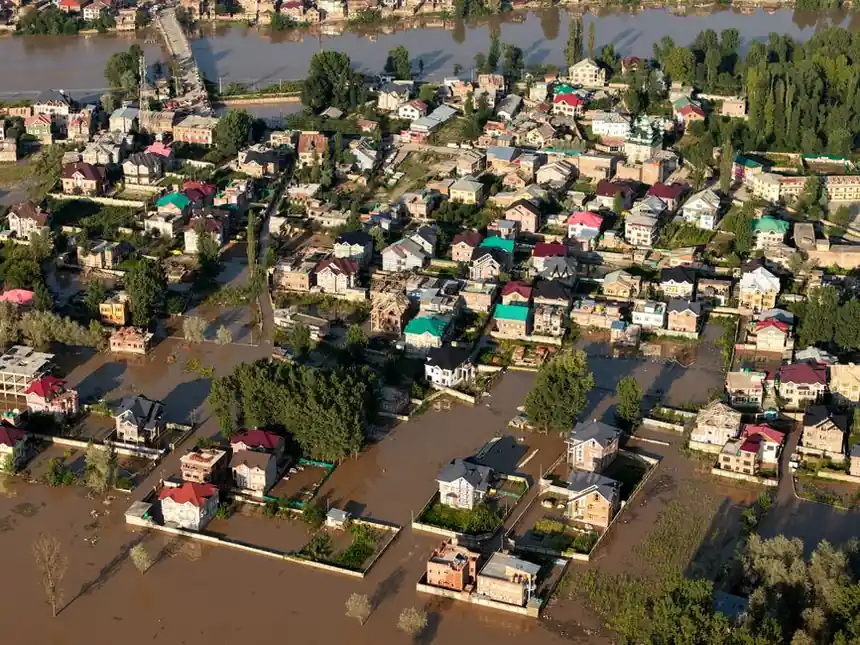
Homeowners insurance in Bradenton does not cover flooding. Flood insurance is a separate policy, usually written through the National Flood Insurance Program (NFIP) or a private carrier, and it is the only policy that pays for rising water entering your home. If you live in Bradenton and a storm pushes the Manatee River or a drainage canal into your living room, your homeowners policy will deny the claim - every time.
Below we break down exactly what each policy covers, what flood insurance costs in Bradenton in 2026, and the mistakes that get claims denied. We've walked through hundreds of flooded homes here, and the insurance confusion is almost always worse than the water.
The short answer: homeowners insurance does not cover flooding
Flood insurance vs homeowners insurance in Bradenton comes down to one word: source. Homeowners insurance covers water that comes from inside your plumbing system - a burst supply line, an overflowing washing machine, a failed water heater. Flood insurance covers water that comes from outside and enters your home from the ground up.
That distinction is written into nearly every Florida homeowners policy as a flood exclusion. It doesn't matter whether the water came from a hurricane, a tropical storm, a king tide, or a blocked storm drain on a sunny afternoon. If the water touched the ground outside before it touched your floor, it's a flood claim.
Bradenton sits between the Manatee River, Palma Sola Bay, and a low-lying coastal plain that drains slowly. We get flood claims from neighborhoods that aren't in a high-risk zone at all - the kind of place where a 4-inch rain in an hour turns a street into a shallow lake.
What homeowners insurance actually covers in Bradenton
Homeowners insurance flood coverage in Bradenton is narrower than most people assume. A standard HO-3 or HO-6 policy pays for sudden and accidental water damage from inside the home, plus wind damage, fire, theft, and liability.
Here's what a typical Bradenton homeowners policy does pay for:
- Burst or broken pipes inside the walls, under the slab, or in the attic - including the water damage that follows
- Appliance failures like a ruptured washing machine hose or a leaking water heater tank
- Wind-driven rain that gets in through a damaged roof or broken window, if the wind damage itself is covered
- Overflow from a tub, sink, or toilet - though sewer backup usually needs a separate endorsement
- Ice maker and supply line leaks behind the refrigerator
Notice what's missing: rising water. Storm surge, river flooding, sheet flow across a yard, and water that backs up through a floor drain during a heavy rain are all excluded. So is sewer backup unless you bought the endorsement - and in older Bradenton neighborhoods with clay sewer laterals, that endorsement is worth the $50 to $100 a year.
If a pipe bursts in your wall, that's a covered claim and our burst pipe water damage repair Bradenton FL team works directly with your adjuster. If the Manatee River comes over the bank, that's a flood claim and a different policy entirely.
What flood insurance covers that homeowners insurance won't
Flood insurance Bradenton Florida homeowners buy through the NFIP covers the building and, optionally, the contents. The building coverage pays to repair or replace the structure - drywall, flooring, cabinetry, electrical, plumbing, and the HVAC system - up to the policy limit.
NFIP limits are set by statute: $250,000 for the building and $100,000 for contents on a residential policy. If your home is worth more than that, or you have a finished lower level, a private flood policy or an excess flood policy fills the gap. Private flood insurance has grown a lot in Florida since 2020 and often costs less than the NFIP for the same coverage.
What flood insurance does not cover:
- Money, valuable papers, and most jewelry
- Finished basements and the contents in them (NFIP excludes basement finished walls and floors)
- Decks, pools, and detached structures unless specifically added
- Mold remediation beyond the limited NFIP allowance
- Loss of use - hotel bills and rent while your home is unlivable
That last one matters. After a major flood, families in Palma Sola water damage restoration territory often spend weeks out of the house, and the NFIP won't pay for a single night of it. Private policies sometimes will.
Do Bradenton residents need flood insurance?
Do I need flood insurance Bradenton? If you have a federally backed mortgage and your home sits in a FEMA Special Flood Hazard Area (Zone A, AE, V, or VE), yes - flood insurance requirements Bradenton lenders enforce mean you must carry it for the life of the loan.
But the mortgage rule is the floor, not the ceiling. About 25% of all NFIP flood claims come from properties outside the high-risk zones. Bradenton is a good example of why. The city has neighborhoods at 6 to 10 feet of elevation that flood from rainfall, not surge, and FEMA maps don't always capture that.
Here's the practical test we give homeowners:
- Is your finished floor within 2 feet of the street or the nearest storm drain?
- Has water ever stood in your yard, driveway, or garage after a heavy rain?
- Is your home built before 1990, when much of Bradenton's drainage was upgraded?
- Do you have a finished lower level, a converted garage, or a sunken living room?
Two or more yes answers and you should be carrying flood insurance regardless of what the map says. The same logic applies to businesses - commercial flood losses are almost never covered by a standard BOP, and our commercial water damage restoration Bradenton FL crews see it every rainy season.
How much does flood insurance cost in Bradenton?
Flood insurance cost Bradenton Florida homeowners pay in 2026 typically runs $700 to $2,400 a year for a single-family home, depending on zone, elevation, and coverage amount. Preferred-risk policies in Zone X often land at the low end - $700 to $1,100 - while Zone AE properties with a low first floor can run $2,000 or more.
Contents-only policies for renters are cheaper, usually $200 to $500 a year for $50,000 to $100,000 of coverage. Private flood carriers sometimes beat NFIP pricing by 20% to 40% on newer homes with a favorable elevation certificate.
Two things move the number more than anything else:
- Elevation certificate. If your home was built to code and you have a current certificate, you may qualify for a substantial discount. A certificate costs $200 to $500 and can pay for itself in the first year.
- Claims history. NFIP now prices repeat-loss properties much higher. One $30,000 claim can triple your premium at renewal.
Compare that to the cost of a flood. A 3-inch flood in a 1,800-square-foot Bradenton home typically means $18,000 to $45,000 in drywall, flooring, cabinetry, and baseboard removal - before mold. The policy is the cheaper number almost every time.
Common mistakes Bradenton homeowners make with flood claims
The most expensive mistake in a flood damage insurance claim Bradenton homeowners make is waiting. NFIP policies have a 30-day waiting period before coverage begins, and once water is in the house, every hour of delay adds damage the adjuster can attribute to neglect.
Here's what we see go wrong, over and over:
- Throwing out the wet stuff before documenting it. Photograph and video every room, every item, and the water line on the drywall before anything leaves the house.
- Calling the insurance company before stopping the water. Mitigation comes first. Your policy requires you to prevent further damage, and the carrier expects to see that you did.
- Assuming the adjuster will find the hidden moisture. Water wicks up drywall 12 to 18 inches above the visible line and soaks into the subfloor. If it isn't documented with a moisture meter, it isn't in the claim.
- Skipping the sewer backup endorsement. A backed-up lateral during a heavy rain is a sewer claim, not a flood claim, and without the endorsement you're paying out of pocket.
- Letting mold sit. Mold can start growing in 24 to 48 hours in a Bradenton home in July. Most policies cap mold remediation, so the faster the structure dries, the more of the claim stays available for the actual repairs.
We handle the documentation side as a matter of course - moisture readings, photo logs, and daily drying records that adjusters accept. That's the same process we run on every residential water damage restoration Bradenton FL job, whether it's a $2,000 ceiling leak or a $60,000 flood.
When to call a professional
Call us when the water is more than a towel can handle, when it has been standing for more than a few hours, or when it has touched drywall, insulation, or subfloor. Those materials don't dry on their own in Florida humidity, and the difference between a $4,000 dry-out and a $40,000 rebuild is usually the first 48 hours.
At Water Damage Restoration Bradenton, we extract the standing water, set drying equipment, and document everything your adjuster needs. We work with both flood and homeowners claims, and we can tell you within the first hour which policy your loss falls under. If you're in a low-lying neighborhood like Bayshore Gardens water damage restoration, we've probably already worked on your street.
For the broader picture of how we handle storm-related losses across the region, see our water damage restoration Bradenton services.
Frequently Asked Questions
What is the difference between flood insurance and homeowners insurance in Bradenton?
Homeowners insurance covers water damage from inside the home, like a burst pipe or failed water heater. Flood insurance covers water that enters from outside - storm surge, river flooding, or rainfall accumulation. In Bradenton, homeowners policies exclude flood damage entirely, so you need a separate flood policy to be covered for rising water.
Does homeowners insurance cover flood damage in Florida?
No. Standard Florida homeowners policies exclude flood damage, including hurricane storm surge and rising water. Wind damage from a hurricane is typically covered, but the water that follows is not. You need a separate flood policy through NFIP or a private carrier, and it has a 30-day waiting period before coverage starts.
Do I need flood insurance in Bradenton FL?
You are required to carry flood insurance if you have a federally backed mortgage on a home in a FEMA high-risk zone (A, AE, V, or VE). Beyond that requirement, about 25% of flood claims come from outside high-risk zones, and much of Bradenton floods from rainfall rather than surge. If your yard or street has ever held water, the policy is worth carrying.
How much does flood insurance cost in Bradenton?
In 2026, most Bradenton homeowners pay $700 to $2,400 a year for flood insurance. Preferred-risk Zone X policies often run $700 to $1,100, while low-elevation Zone AE homes can exceed $2,000. Renters can get contents-only coverage for $200 to $500 a year. An elevation certificate can lower the premium significantly.
What does flood insurance cover in Bradenton?
NFIP flood insurance covers building damage up to $250,000 and contents up to $100,000 on a residential policy. That includes drywall, flooring, cabinetry, electrical, plumbing, and HVAC. It does not cover finished basements, loss of use, or most mold remediation beyond a limited allowance. Private policies can add those coverages.
Get help with water Damage Restoration Bradenton in Bradenton
Whether your loss is a covered pipe burst or an excluded flood, the water has to come out now. We'll tell you which policy applies and start drying your home the same day. Call +17253098505 and we'll be on our way.